Bankroll Management Protecting Your Betting Capital
 Available in US
Every sports bettor eventually learns the same painful lesson: you can pick winners all day and still go broke through poor money management. The ability to identify good bets means nothing if improper staking wipes out your bankroll before the long-term edge materialises. Bankroll management is not glamorous – nobody brags about their conservative staking approach – but it separates sustainable bettors from those who flame out after a few bad weeks.
Your bankroll is your inventory, your working capital, your lifeline to continued participation in the betting markets. Treating it carelessly is equivalent to a business owner burning through cash reserves on speculation. Professional bettors understand that survival comes first; profits come second. You cannot win long-term if you are not around for the long term, and aggressive staking during inevitable losing streaks destroys bankrolls with alarming speed.
The mathematical reality of sports betting makes bankroll management non-negotiable. Even skilled bettors with genuine edge win only 53-56% of spread bets. This means roughly half of all bets lose regardless of skill level. Variance ensures that losing streaks of 10, 15, even 20 consecutive bets will occur over sufficient volume. If your staking cannot survive these inevitable drawdowns, your edge is worthless.
Table of Contents
Establishing Your Bankroll
Your betting bankroll should be money specifically set aside for wagering – funds you can afford to lose entirely without affecting your life. This is not discretionary income you might need for bills, not savings earmarked for other purposes, not money borrowed or otherwise encumbered. It is capital dedicated to the betting endeavour with full acceptance of potential loss.
How much constitutes an appropriate bankroll depends on your betting goals and financial situation. Recreational bettors seeking entertainment might start with $500 to $1,000, accepting that this money is essentially an entertainment expense like a concert ticket or vacation budget. Serious bettors attempting to generate consistent profit typically work with $5,000 to $25,000 or more, recognising that smaller bankrolls limit bet sizing and thus potential returns.
Once established, your bankroll exists as a separate entity from your regular finances. Winnings get reinvested into the bankroll rather than withdrawn for spending. Losses reduce the bankroll, which automatically reduces bet sizes as a protective mechanism. This separation prevents the emotional tendency to chase losses with money you cannot afford to lose or to prematurely withdraw profits that should compound.
Deposit your bankroll across multiple sportsbooks rather than concentrating it at one. This serves multiple purposes: it enables line shopping, protects against book failures or account limitations, and psychologically separates betting capital from everyday accounts. Having $5,000 spread across five books at $1,000 each is safer and more functional than $5,000 at a single book.
Unit-Based Staking
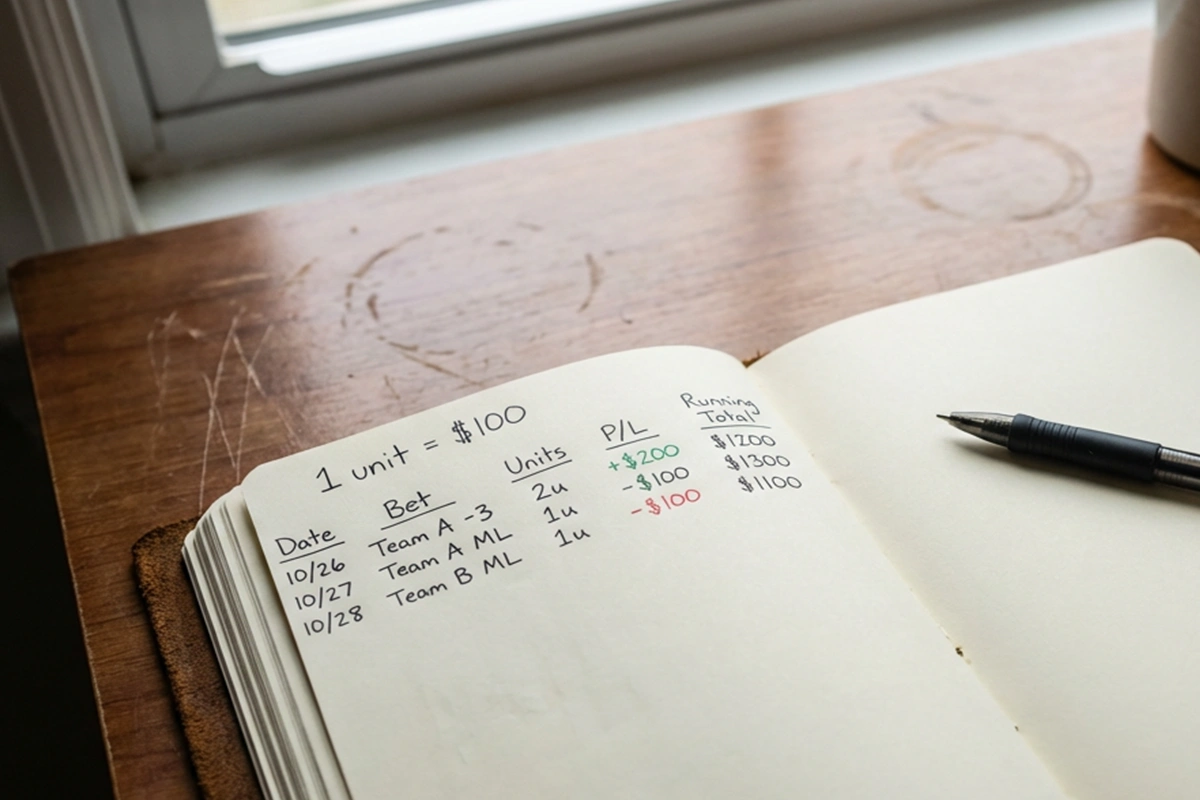
The unit system provides a standardised approach to bet sizing that scales with your bankroll. A unit represents a fixed percentage of your total bankroll – typically 1% to 3% for most bettors. If your bankroll is $5,000 and your unit is 2%, each unit equals $100. All bets are then expressed in units rather than dollar amounts.
Using units accomplishes several things. It creates consistency across different bet types and confidence levels. It automatically adjusts bet sizes as your bankroll grows or shrinks. It provides a common language for tracking and discussing results. And it prevents the dangerous tendency to bet arbitrary amounts based on emotional reaction rather than systematic calculation.
Most disciplined bettors risk between 1 and 3 units on standard plays. A 1% unit (1 unit = 1% of bankroll) is conservative, protecting the bankroll but limiting profit potential. A 3% unit is more aggressive, growing the bankroll faster during winning periods but risking larger drawdowns during losses. Many bettors settle on 2% as a reasonable compromise.
Some bettors vary their unit size based on confidence level – betting 2 units on strong plays and 1 unit on standard plays. This graduated approach has intuitive appeal but requires honestly calibrated confidence. If your “2-unit” plays do not actually win at higher rates than your “1-unit” plays, the graduated system just increases variance without improving results.
The Kelly Criterion
The Kelly Criterion represents the mathematically optimal staking approach for maximising long-term bankroll growth. Developed by Bell Labs researcher John Kelly in 1956, the formula calculates ideal bet size based on your edge and the odds offered. The core insight is that you should bet more when your edge is larger and less when it is smaller, with the formula precisely quantifying these relationships.
The basic Kelly formula is: (bp – q) / b, where b is the decimal odds minus 1, p is your probability of winning, and q is your probability of losing (1 – p). The result is the percentage of your bankroll to wager. For example, if you estimate 55% win probability on a -110 bet (1.91 decimal odds), Kelly recommends betting approximately 6% of your bankroll.
In practice, full Kelly staking is too aggressive for most bettors. The formula assumes perfect probability estimates, which nobody has. Overestimate your edge slightly, and full Kelly recommends bet sizes that will devastate your bankroll when variance strikes. A bettor using full Kelly has approximately a 1-in-3 chance of halving their bankroll before doubling it – uncomfortable odds for most.
Fractional Kelly approaches address this volatility. Half-Kelly stakes exactly half the amount full Kelly recommends; quarter-Kelly stakes one-quarter. These conservative modifications sacrifice maximum growth rate for reduced variance and greater bankroll stability. Most professional bettors use somewhere between quarter-Kelly and half-Kelly, accepting slower growth in exchange for reduced risk of ruin.
The Kelly Criterion requires accurate probability estimates to function properly. If you consistently overestimate your edge – a common error among recreational bettors – Kelly will recommend oversized bets that compound your mistakes. The formula is only as good as the inputs, and honest assessment of your actual edge is prerequisite to useful Kelly calculations.
Flat Staking Approach
Flat staking takes a simpler approach: bet the same amount on every wager regardless of perceived edge or confidence. If your unit is $100, every bet is $100 – no variation, no graduated systems, no Kelly calculations. This approach sacrifices theoretical optimality for simplicity and psychological stability.
The case for flat staking is stronger than sophisticated bettors often acknowledge. It eliminates the temptation to overbet on “sure things” that inevitably lose sometimes. It prevents the creeping stake inflation that destroys bankrolls when bettors convince themselves each new bet deserves extra confidence. It provides consistent risk exposure and predictable variance.
Flat staking is particularly appropriate for bettors who cannot accurately assess their edge on individual bets. If you do not know whether your edge on a particular bet is 2% or 5%, any graduated staking system just adds noise. Betting the same amount on every +EV opportunity you identify captures value consistently without the risks of miscalibrated confidence.
The flat staking approach also simplifies record-keeping and performance evaluation. When every bet is the same size, your unit profit or loss directly reflects your edge. Varying stakes complicates this – a 10-unit loss during a 7-3 week obscures what would be good results with flat stakes.
Avoiding Catastrophic Mistakes
Certain bankroll management errors devastate bettors regularly. Understanding these failure modes helps you avoid them.
Chasing losses destroys more bankrolls than any other single error. After a losing day or week, the temptation to increase stake sizes to “get back to even” is almost irresistible. This guarantees larger losses during extended downturns, converting normal variance into catastrophic drawdowns. The proper response to losing streaks is maintaining or reducing stake sizes, not increasing them.
All-in mentality occasionally tempts bettors who have fallen so far behind that only a big win can save their bankroll. This desperation bet almost always fails, and even if it wins, the underlying psychology leads to eventual ruin. Bankroll management exists to prevent situations where all-in bets seem necessary.
Parlays as primary strategy effectively circumvents bankroll management by concentrating risk into low-probability, high-reward bets. A bettor who carefully limits singles to 2% of bankroll but fires 10-leg parlays regularly is not actually managing their bankroll – they are gambling on unlikely outcomes while pretending discipline exists.
Ignoring losing streaks by pretending they are anomalies rather than inevitable occurrences leads to inadequate preparation. Every serious bettor will experience 10-bet losing streaks, 15-bet losing streaks, potentially longer. Your staking must assume these will happen, not optimistically hope they will not.
Lifestyle creep from betting profits creates dangerous pressure. If you begin depending on betting income for regular expenses, you become psychologically unable to handle normal variance. The rent payment depending on this week’s results creates decision-making pressure that destroys disciplined staking. Keep betting separate from life finances.
Practical Implementation
Start by determining your total betting bankroll – money specifically allocated for wagering that you can afford to lose. Write this number down as your starting bankroll. Choose your unit size: 1% for conservative, 2% for moderate, 3% for aggressive. Calculate your unit in dollars.
Track every bet including stake, odds, result, and running bankroll total. Recalculate your unit periodically – monthly or quarterly – based on current bankroll. If your bankroll has grown, your unit grows proportionally; if it has shrunk, your unit shrinks. This automatic adjustment protects during drawdowns and captures compounding during winning periods.
Set loss limits that trigger reflection rather than panic. If your bankroll drops 25% from its peak, review your process. Are you making good bets that are simply experiencing variance? Or are you betting poorly and the results are reflecting that? If the answer is variance, maintain discipline. If the answer is poor betting, reduce activity until you identify the problem.
Never deposit more money to replace bankroll losses without serious analysis. Adding funds to a declining bankroll often just feeds a losing strategy. If your approach is sound and variance is the cause, the bankroll will recover naturally. If your approach is flawed, additional deposits just provide more money to lose.
Consider separating your bankroll by sport or bet type if you have different skill levels across markets. Your NFL handicapping might merit 2% units while your less-developed NBA analysis might warrant 1% units. This acknowledges different edges in different markets.
Bankroll management is ultimately about emotional control as much as mathematics. The formulas and percentages mean nothing if you abandon them during the heat of a losing streak or the euphoria of a winning run. Commit to your system before the variance hits, and maintain discipline when it does. Your long-term results depend more on this commitment than on any individual bet you will ever place.